October 11, 2026 · 6 min read · By Exec Armor
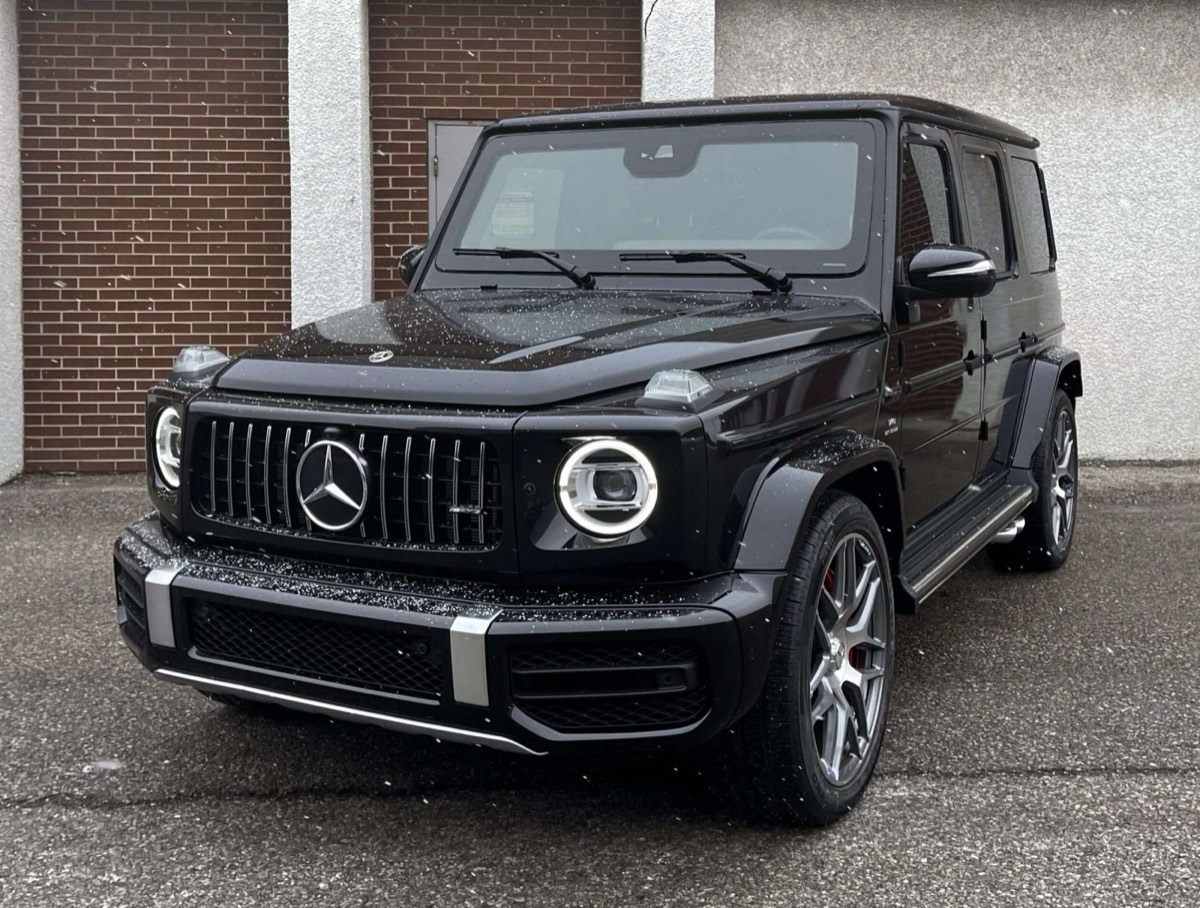
One of the most common questions we hear after “how much does it cost” is “can I even insure it?” The short answer is yes — insuring an armored vehicle is routine, and with the right documentation it is no harder than insuring any high-value car. Here is how it works.
Which carriers insure armored vehicles
Standard mass-market insurers often decline armored vehicles simply because they do not understand them. The right home is a high-net-worth or specialty carrier: Chubb, AIG Private Client, Aviva Private Clients and the private-client arms of the major global insurers routinely write armored vehicles. For fleet and institutional clients — cash-in-transit operators, diplomatic missions, corporations — Lloyd’s syndicates, Allianz Global Corporate & Specialty, Zurich and Munich Re recognise professionally-built armored vehicles at standard specialty rates.
How the vehicle is valued
An armored vehicle is insured on an agreed-value basis, not a depreciated book value. The declared value is the base vehicle plus the armoring plus any bespoke interior work. This is where the documentation we provide matters: every Exec Armor build ships with an itemised specification that separates base-vehicle value from armoring value, plus the ballistic-test certification. Underwriters use this to set agreed value accurately — so in a total-loss event you are made whole on the full armored value, not just the car.
What premiums look like
Premiums run modestly above the unarmored equivalent — typically a single-digit to low-double-digit percentage uplift, driven mostly by the higher insured value rather than by added risk. In practice, armored vehicles often present lower physical risk (reinforced structure, run-flat tires, upgraded brakes), which thoughtful underwriters recognise. Factors that move the premium: insured value, where the vehicle operates, who drives it, and storage/security arrangements.
What is and isn’t covered
Comprehensive and collision coverage work normally. A ballistic event — an actual attack — is typically covered under comprehensive, which is exactly what the vehicle is for. What a vehicle warranty covers is different from what insurance covers: our 24-month armor warranty covers manufacturing integrity (delamination, bond failure, premature corrosion), while insurance covers damage from events. Keep the two straight and you are never caught short.
Documentation checklist
- Itemised build specification (base vehicle vs. armoring value)
- Ballistic-test certification (CEN and/or NIJ)
- Chain-of-custody and engineering drawings of the ballistic envelope
- Proof of protection level and manufacturer credentials (ISO 9001, validation)
Exec Armor supplies all of this with every vehicle, and our team can speak directly with your broker or underwriter to answer technical questions. If you are weighing total cost of ownership, pair this with our armored vehicle cost breakdown, then book a consultation.
About Exec Armor. We have manufactured custom armored vehicles in Vaughan, Ontario since 2010 — over 500 vehicles delivered to clients in more than 40 countries. CEN BR4–BR7 ballistic protection, ISO 9001 manufacturing, NIJ III & IV equivalent, independent ballistic validation and a global warranty network. Book a free consultation.